Lowest premiums,
Highest Touch.
We use our extensive Aviation knowledge and insurance expertise to educate the insurance carriers about your business so that you receive the best policies each year backed by transparent market options.
- What are you insuring?
Specialized aviation insurance for private aircraft owners, pilots and businesses who expect more.
Insurance, without the ordinary.
We are proud to provide a wide range of aviation insurance products and services. We offer coverage ranging from aircraft hull and liability insurance to workers compensation and managed fleet policies.
Aircraft Insurance
Individual aircraft owners, multi-owner partnerships, corporations and flight departments.
Comprehensive insurance solutions tailored for personal, commercial, and executive aircraft fleets—ranging from entry-level piston singles to high-performance turboprops and business jets.
Helicopter Insurance
Individual rotorcraft owners, corporate flight departments, training academies, charter fleets, and mission-specific operators.
Customized insurance strategies for personal and commercial rotorcraft operations. These solutions are engineered to address the unique variables of your aircraft, crew, geographic region, and mission profile.
Flight School Insurance
Professional flight schools, university aviation departments, aircraft rental operations, independent CFIs, and flying clubs.
Strategic insurance frameworks developed for aviation academies, collegiate flight programs, rental businesses, and flying clubs. These programs are structured to reduce the insurance cost load and provide easy to understand protection for multi-pilot and aircraft environments.
Charter and Managed Fleet Insurance
Commercial charter operators, fleet management companies, corporate flight departments, and multi-aircraft air-taxi services.
Strategic insurance frameworks designed for air-taxi businesses, Part 135 operators, and professional aircraft management firms. These programs are structured to protect diverse fleets and the complex operational risks of managed aviation assets.
FBO & Ground Operations Insurance
Fixed Based Operators, Airport Service Providers, fueling operations, ground handlers, and privately operated airports.
Coverage for the combination of services an FBO provides, including fueling, ramp services, aircraft storage, ground handling, and customer facilities.
Aircraft Maintenance & Mechanic Liability
A&P mechanics, independent mobile technicians, certified repair stations, MRO providers, avionics specialty shops, and component overhaul facilities.
Liability coverage developed for aviation maintenance organizations and technicians specializing in aircraft inspection, airframe repair, and component overhaul. These programs are structured to protect the integrity of your technical operations and specialized service facilities.
Hangar & Aviation Property Insurance
Hangar owners, hangar tenants, aircraft storage businesses, FBOs, and maintenance facilities.
Protection for hangar buildings, office space, tools, equipment, inventory, and other aviation-related property.
Aviation Workers’ Compensation
Flight Schools, Part 135 Operators, Fixed Base Operators (FBO), aircraft management firms, and maintenance facilities.
Workers’ Compensation policies engineered specifically for the aviation sector. These programs provide essential protection for personnel operating across flight lines, within maintenance hangars, or aboard active aircraft using specialized mission equipment.
Renter’s & CFI Non-Owned Insurance
Student pilots, recreational pilots, renters, borrowers, and certified flight instructors.
Personal protection for pilots and instructors who rent, borrow, or instruct in aircraft they do not own. The aircraft owner’s or flight school’s policy may not provide complete protection for the individual pilot.
Meet Joe
- Ready for Insurance? Call Joe

Insurance should feel personal.
Joe Ryan is an aviation insurance broker, professional pilot, and business owner with 15 years of industry experience. Before founding his own aviation insurance brokerage, Joe worked for one of the nation’s largest aviation specialty firms, where he built a reputation for technical expertise, responsive service, and personal client relationships.
His aviation career has included roles as an airline and corporate pilot and as the lead flight instructor at a now Platinum Cirrus Training Center. A graduate of the University of North Dakota’s Aerospace program, Joe holds ATP and CFII ratings and has logged several thousand flight hours. He is a frequent speaker at aviation conferences, podcasts, and owner/operator events, sharing practical insights on insurance, training, and safety management.
Raised on a farm as one of ten children, Joe brings a grounded, hardworking approach to his business. Outside the office, he enjoys golf, reading, and life with his pilot wife (who is cooler than him) and golden retriever, Ernie
Listen to Client Voices
Joe Ryan did an outstanding job finding the right aviation insurance for our large flight school fleet, Chennault Flying Service, and my personal aircraft. He...
Joe has been a genuine ally as we’ve grown our business and our fleet. He’s responsive, takes the time to understand our needs, and works...
Joe Ryan has been a trusted insurance broker for our business. He takes the time to understand our operation, explains our options clearly, and follows...
I’ve been fortunate to work with the Joe Ryan for my aviation insurance needs for several years, across multiple aircraft. Joe has worked hard to...
Joe and his team provide expert aviation insurance guidance. They provide the ‘why’ behind insurance coverage, and consult with their clients on risk strategy. I...
As an aircraft broker, providing my buyers with the right insurance policy can often make or break the transaction. I have referred buyers to Joe...
Knowledge worth taking with you.
Practical guidance from a specialist who has spent their entire career in aviation.
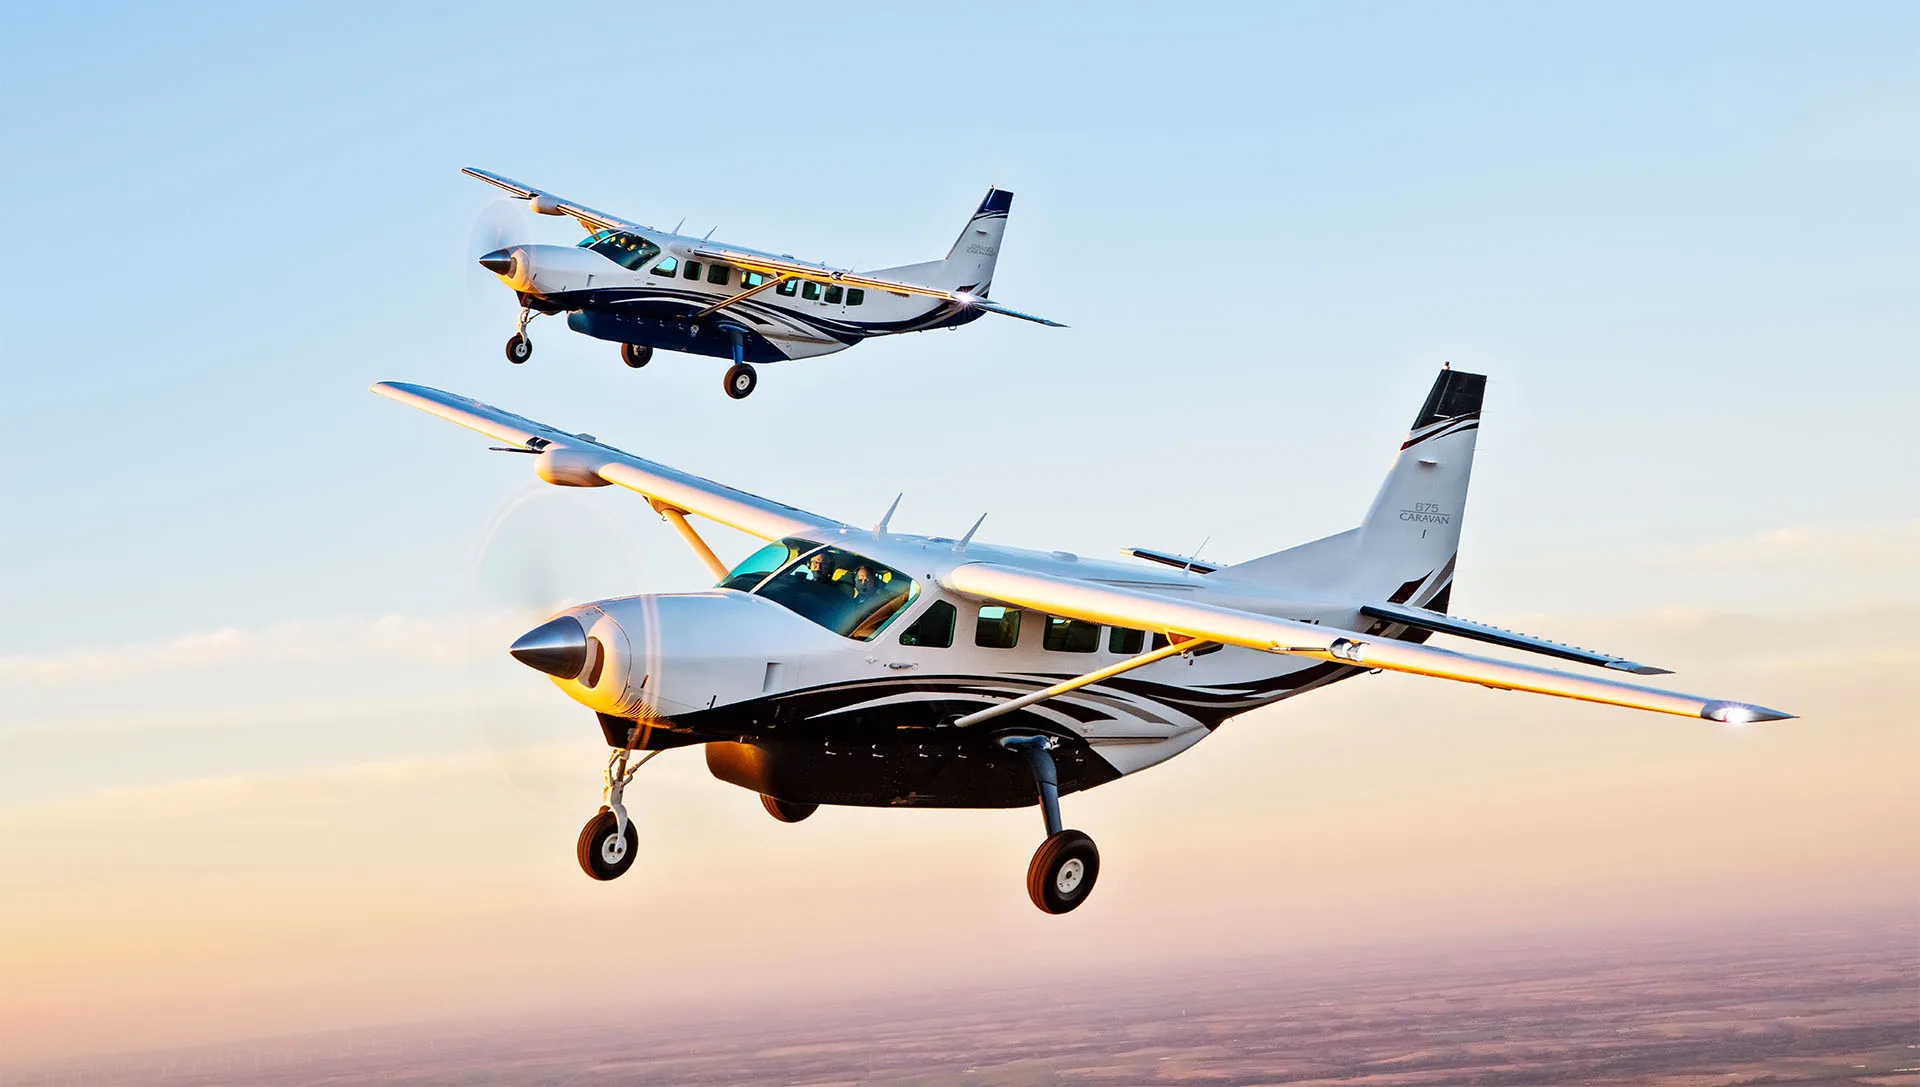
Moving From a Piston Aircraft To a Turboprop or Jet
Owning a private aircraft is a significant investment, and the right insurance coverage is essential to protecting both the aircraft and your financial interests. From hull and liability coverage to pilot requirements, exclusions, and geographic limits, aircraft insurance can be more complex than standard policies.
Understanding what your policy actually covers can help you avoid costly surprises when you need it most.
What You Need To Know
Is aircraft insurance like car insurance?
Not really. Car insurance is a huge market where you can call a dozen companies in an afternoon and get quotes. Aviation insurance is a small, specialized market with only a couple dozen underwriters, and almost all of them work only through specialist brokers. It also runs on a broker-of record system: the first broker to take your aircraft and details to an underwriter represents you with that underwriter. That means calling several brokers doesn’t get you more quotes. It just creates confusion. The best move is to work with one independent aviation specialty broker who can represent you to the entire market.
I got a quote via phone, can I bind that once I close on my aircraft?
A quote via phone may be a brokers estimation of the premium, training requirements, and terms based on their experience or best guess. This type of estimation can be useful when you’re researching a purchase or budgeting for an upgrade. Firm terms come after a full application goes to the underwriters, and the final number can move up or down depending on the details they review like aircraft type and value, pilot age, total time, make and model time, state location, liability limits, and use. Be aware of the limitations of verbal estimations of insurance if you are looking for accurate premiums and training requirements.
How long does it take to get a quote?
A full market review takes about 4 to 5 business days once I have your completed application. Faster quotes, even same-day, are possible, but you’ll only see the first underwriters to respond, not the whole market. Underwriters prioritize requests with a coverage date within 30 days, so if you’re buying, reach out early. Moving into a turbine that requires initial training? Start 60 to 90 days before closing so you can book an approved training provider before they fill up.
Can I dry lease my aircraft or rent it?
Often yes, and some policies include endorsements that allow you to rent your aircraft to specific pilots. Regardless of the arrangement, tell your broker before you do it. A dry lease to another person or entity under Part 91 is common. The underwriter may need to add the lessee to the policy, sometimes for an added fee. If you’re looking to operate commercially or making a profit you should speak with a knowledgeable aviation attorney. If you’re putting your aircraft on a flight school’s leaseback line, the school’s policy usually covers it. Make sure you get a leaseback owner certificate naming you as additional insured, with a waiver of subrogation, and as loss payee.
Why did my premium change this year?
Several things move a premium: how many underwriters competed for your business (limited by the amount of underwriters a broker is contracted with), changes in your experience, claims history (yours and the industry’s), your aircraft’s value, and how you use the aircraft. Getting your policies in front of every underwriter can provide the best chance at a favorable premium no matter what the overall insurance market is doing.
What is a named pilot?
A named pilot is someone listed by name on your policy and approved by the underwriter. Most policies also have an open pilot warranty, which covers any pilot who meets set minimums, such as certificates, ratings, and hours, without being named. If someone you want flying your aircraft doesn’t meet every part of that warranty, such as a new CFI or a lower time family member, they need to be named. That usually just means filling out a short pilot form and having your broker approach underwriting for approval. Since most policies are rated based on the lowest experienced pilot, keep in mind that the premium can change if a less experienced pilot is named.
What insurance companies do you represent?
Ryan Aviation Insurance is an independent aviation broker and can place business with every A rated aviation insurance carrier. As an independent aviation brokerage, we represent you and your interests. We take your policy to every market that writes your type of risk, then lay the options side by side so you can compare coverage and price.
Will my premium drop as I build hours?
Usually, yes. Underwriters price heavily on experience, and certain milestones tend to open up better rates and more markets. Common ones are time in your make and model (often around 100 hours), total time thresholds like 300, 500, 750, and 1,000 hours, and about 250 hours of multi-engine time for twins. Adding an instrument rating, additional certificates, and staying current with recurrent training help too. The first year in a new aircraft is typically the most expensive.
How much liability do I need?
It depends on who you fly with. A common starting point for piston aircraft is $1 million per occurrence with a $100,000 limit per passenger. When available, a combined single limit (CSL) is usually the better choice, because it doesn’t cap what’s paid per passenger. If you regularly fly business associates, clients, or friends with significant assets, higher limits are worth a hard look, since aviation liability often isn’t picked up by your other policies.